
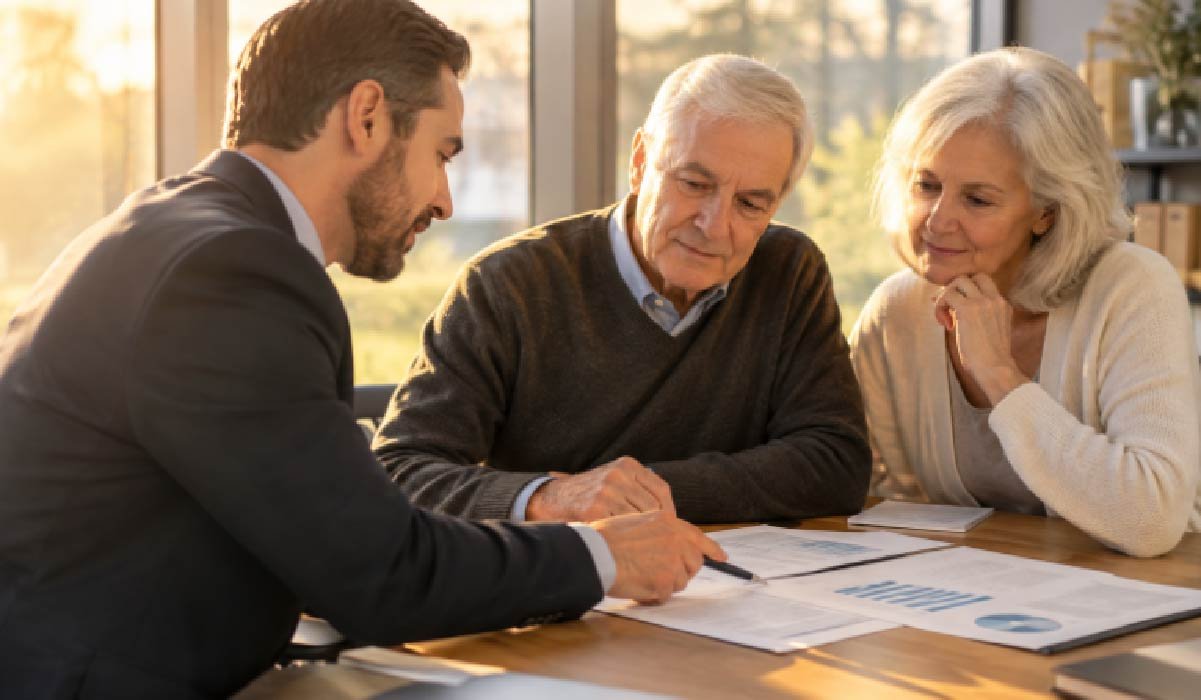
Financial Advisors should expect more detailed questions about fees as client reporting becomes easier to read. The right response is not to become defensive or rely only on investment performance. It is to prepare clients for a transparent discussion about costs, planning, and the decisions that shape their financial lives. A planning-focused total cost reporting software approach can help make those conversations more organized and relevant to each client. Clients rarely view fees in isolation. They also want to know what they received, what decisions were made during the year, and whether their plan is still aligned with the future they want. Annual reviews are an opportunity to answer those questions clearly, before confusion turns into concern.
Why Fee Conversations Need a Fresh Approach
Clearer reporting can bring attention to charges that clients may not have previously noticed or understood. That does not mean every discussion has to be difficult. It means Advisors should be ready to explain the numbers in context, including direct charges, investment product expenses, and the scope of advice and service provided. Most clients will want straightforward answers to a few core questions: How much did I pay? What was included? Which costs were part of my investments? What work was completed for me? How does this support my goals? A good review anticipates these questions rather than waiting for a client to raise them.
Reporting Fees Is Not the Same as Explaining Value
A statement can show a dollar amount without showing the planning behind it. Advisors should distinguish between investment-related expenses and the broader work involved in a relationship, such as retirement income planning, cash flow analysis, tax-aware decision-making, insurance reviews, estate coordination, and behavioral coaching during volatile markets. Specific examples are more useful than broad claims. For example, an Advisor might explain how a retired couple adjusted withdrawals after a market decline, reviewed their income sources, and tested whether their spending plan remained sustainable. The goal is not to promise a better return. It is to show the decisions considered, the risks reviewed, and the rationale for the chosen path.
Prepare Before the Annual Review
A repeatable preparation process helps Advisors enter meetings with confidence. Before meeting with a client, review the following:
- Current accounts, investments, and service arrangements.
- Major decisions made since the previous review.
- Planning work completed, including cash-flow, tax, risk, retirement, or estate discussions.
- Any assumptions that need updating, such as retirement timing, spending, income needs, or family circumstances.
- Two or three examples that demonstrate advice in action for that specific client.
- Likely questions about fees, performance, and next steps.
Use Plain Language and Goal-Based Conversations
Technical language can make a client feel excluded from an important discussion. Define acronyms before using them, explain percentages alongside dollar amounts, and avoid phrases that sound promotional or dismissive. Instead of saying a portfolio has a certain expense ratio, explain what the cost represents and where it appears in the client’s reporting. Then move the conversation to the client’s priorities. Ask what matters over the next one, five, and ten years. Review retirement income, education funding, business plans, estate intentions, or other personal goals. When trade-offs exist, explain them honestly. A client may choose to spend more now, retire later, save more, or accept a different level of investment risk. The Advisor’s role is to clarify those choices, not pretend there is a perfect answer.
Use Visuals That Make Decisions Easier to See
Long reports can overwhelm clients, particularly when every figure appears equally important. A one-page summary or side-by-side scenario can make the meeting more useful. Show how a change in savings, withdrawals, retirement timing, or spending could affect a projection, while making clear that projections are estimates rather than guarantees. Simple visuals also help clients connect advice to real decisions. Focus on the few figures that matter most, such as estimated retirement income, expected cash flow, tax impact, or the effect of a planned change. The client should leave knowing what was discussed, why it matters, and what happens next.
A Five-Step Framework for Fee Discussions
- Invite questions: Ask what stood out to the client in their report.
- Clarify the figures: Explain each major cost in direct, understandable terms.
- Review the work: Summarize planning, service, and decisions completed during the year.
- Connect advice to goals: Relate the discussion to the client’s priorities and trade-offs.
- Confirm next steps: Record actions, owners, and timelines before the meeting ends.
What Canadian Advisors Should Know About Total Cost Reporting
Canadian reporting changes are intended to make ongoing investment fund and segregated fund costs more visible to clients. The clearer view of investment fund expenses and other charges described for investors is a useful reason to improve communication before enhanced reports are received. Canadian regulators have stated that the first enhanced annual reports are to be delivered for the calendar year ending December 31, 2026. The implementation process for these reporting enhancements also shows why firms should align their client education, internal definitions, and meeting processes early.
Common Mistakes to Avoid
- Waiting for the client to bring up fees first.
- Using investment performance as the only evidence of value.
- Presenting many figures without explaining their meaning.
- Defending a charge before listening to the client’s concern.
- Making promises about returns or outcomes that cannot be guaranteed.
- Failing to document questions and follow-up commitments.
Handling Difficult Client Questions
“Why did I pay this much?”
Review the charge carefully, then explain the related services, planning work, and decisions completed during the year. Give the client time to ask follow-up questions.
“Could I pay less somewhere else?”
Acknowledge that lower-cost options may exist. Compare the services, planning scope, support, and responsibility involved without criticizing alternatives.
“Did the advice improve my outcome?”
Discuss the decisions supported, risks addressed, tax considerations reviewed, and progress toward stated goals. Avoid claiming that advice can eliminate losses or guarantee results.
Create Consistency Across the Firm
Firms can strengthen these conversations by using a shared meeting checklist, common definitions for charges, and a consistent way to record client questions. Team members should be trained to explain concepts naturally rather than reciting scripts. Review recurring concerns each quarter, update educational materials as reporting changes occur, and measure improvement through completed reviews, timely follow-up, client feedback, and engagement.
Make Clarity Part of the Service
Transparent fee discussions do not need to create tension. When Advisors explain costs early, speak plainly, and connect their work to client goals, annual reviews become more useful and more human. In 2026, clarity about both the numbers and the advice can be an important part of a strong long-term client relationship.
Conclusion
Clear fee conversations help clients understand not only what they pay but also the planning, guidance, and services they receive in return. By preparing before annual reviews, explaining costs in plain language, and connecting advice to individual goals, Financial Advisors can make complex reports easier to understand and discuss. Visual tools, specific examples, and consistent firm-wide processes can further support transparency and build trust. As total cost reporting evolves in Canada, preparing clients early and addressing their questions openly can make annual reviews more productive. Ultimately, a thoughtful approach to fees helps clients make informed decisions and strengthens long-term relationships through clear communication, realistic expectations, and personalized financial guidance.
